Carta Finds First Hires Taking 1.75% of Startup Equity
On this page 6 sections
AI-generated editorial illustration.
On October 28, Carta put a number beside a startup’s first employee: a 1.75% median initial equity grant among the first hires recorded on its platform over the previous two years. At the 75th percentile, the grant reached 4.26% of fully diluted company equity. The company published the figures in its H1 2026 startup compensation report. They describe grants in Carta’s customer records, not an offer every founder should make or money the employee can spend.
At a four-person seed-stage startup, 1.75% can reshape the hiring plan. Carta’s earlier report put the median seed-stage team on its platform at four employees. A first hire may write the product, sell it, manage implementation, or build the hiring system that lets other people join. The same founder may need room for the next three hires, a financing round and a credible cash salary. The percentage has to fit all of those decisions.
For the person receiving it, a percentage is only the beginning. The grant may be options rather than stock, it may vest over years, and private shares may be hard to sell. The employee can bear a real salary sacrifice without receiving a liquid asset in return. The offer meeting should get past the big percentage. Both sides need to know the work, the share count and the terms that could change its value.
A median from one platform, not a market rate
Carta’s October report is unusually useful because it states a distribution point rather than a single illustrative package. The median first-hire grant was 1.75% and the 75th percentile 4.26% across the two-year cohort on Carta. The difference between those figures is large enough to warn against treating the median as a cap. It also says nothing about the bottom quarter, the compensation mix or the grant for a particular role. The public summary does not publish the count of first hires in that comparison, a geography-by-stage breakdown or the raw distribution. The full report is offered through a form; the openly published summary is the evidence used here.
The same report records a broader change in who receives compensation growth. Since the start of 2024, Carta’s median salary benchmark for new individual contributors one level below senior rose 18.5%, while their median initial equity grant rose 25.4%. Senior directors’ corresponding changes were 6.3% and 3.9%. The median new-hire salary for a senior director in H1 2026 still exceeded twice that of the junior-adjacent IC cohort. A change in the rate of compensation growth does not mean the IC now earns more than the director.
Carta’s analysts connect this pattern to flatter organizations and more capable individual contributors in an AI economy. That is an interpretation of the company’s customer data, not an experiment proving that AI caused the grants to rise. Other pressures can move pay: competition for product and engineering talent, financing conditions, location, changing customer composition and the age of startups in the sample. The report’s own hiring data complicate a simple story of machines replacing workers. In June, companies on Carta made 1.49 hires per departure and recorded 8,570 net hires. The report says new hires had outnumbered departures for 30 consecutive months, while growth remained slower than in 2018 to 2022.
No founder can set an offer from that aggregate alone. Carta also reports a $180,600 median salary benchmark for new product hires and a roughly 0.024% median initial equity grant in that function. Those figures include product hires at many company stages and hiring positions. They do not describe the same cohort as the first-hire 1.75%. Putting the two percentages in one offer spreadsheet as if they were competing quotes would mix unlike jobs and company ages.
First hire is a job description before it is a percentage
Illustrative scenarios, not reported companies or meetings: two founders can build a product but cannot support its first customers; an engineer could take that operating responsibility. Another team may need someone to sell the product or connect it to customer systems. Each hire would join early, but the work and authority would differ. An equity benchmark does not write the job description.
The site’s August examination of first recruiters offers a contrast. Viktor’s August founding-recruiter advertisement described a 25-person company with 25 open roles and a plan to reach 50 to 70 people within six months. That is a first recruiter, not a company’s first employee. The advertisement described future ownership of intake, agency coordination and hiring operations; it did not disclose an equity offer or prove the hiring plan had been realized. A specialist title alone cannot price ownership.
Start with the bottleneck, then discuss the percentage. Is the founder unable to keep a service running while selling? Is a customer launch delayed because implementation has no owner? Does a specialized engineer bring knowledge the founders lack? The answer changes the time horizon. Work that creates a reusable capability over years can support a different ownership case from a short contract to finish one project. A contractor may solve the immediate problem without taking the same long-term bet, though the cash bill and handoff risk differ.
LinkedIn’s October 27 research adds the scale around this decision. It found that founders of startups launched in 2024 employed 26% fewer people after their first year than founders of 2021 startups. It also found founder among the ten fastest-growing roles in five economies during July through September 2026. These are platform observations, not a count of viable new companies or proof that AI caused smaller teams. But fewer seats after the first year can make each early role broader. Broad roles need careful compensation design because there are fewer colleagues to absorb work when one person leaves.
That does not mean every lean company should grant a larger slice. A smaller team might have less cash to offer, more risk, less liquidity and a weaker ability to mentor the first employee. The first hire could face more work without more decision authority. A founder who asks a worker to behave like a cofounder while reserving all consequential decisions for the founders is buying responsibility without transferring control. The grant should be discussed beside the role’s actual scope, access and authority.
Put the grant against the whole option pool
The offer email may say 1.75%. The cap table must say what that means. A founder should know the fully diluted share count used for the grant, the existing option pool, promised but unissued awards, SAFEs or convertible instruments, and whether a financing round or pool expansion is imminent. The employee needs the grant’s share count and the same denominator at the same date. Otherwise two parties can say “1.75%” while imagining different cap tables.
The SEC’s small-business explanation of startup securities makes the first distinction: a stock option is a right to buy a specified number of shares at an agreed price after vesting, not a share that has already been paid out. The Carta option-pool guide explains that a reserve is not outstanding stock; an option grant moves a claim from the reserve to a person, and a later exercise changes the form of ownership. These mechanics matter to a founder allocating a finite hiring budget and to an employee evaluating the offer.
Here is an illustrative worksheet, not a reported offer. It does not describe a Carta company, a recommended pool size, a real offer, or the expected path of any employee. Assume ten million fully diluted shares before a new financing, with 1.2 million shares reserved for employee options. Ignore SAFEs, refresh grants, taxes, preferences and any pool top-up so the denominator change is visible.
| Decision point | Simplified shares and ownership | What the reader should check |
|---|---|---|
| Before the first grant | 10,000,000 fully diluted shares; 1,200,000 reserved options, or 12% | Confirm the denominator and all already promised grants. |
| First hire at the Carta median | 175,000 options equal 1.75% of that denominator; 1,025,000 remain in the reserve | Confirm whether 175,000 is the actual board-approved grant and what it can vest into. |
| First hire at Carta’s 75th percentile instead | 426,000 options equal 4.26%; 774,000 remain in the same reserve | A high initial grant leaves less room for later hires unless the pool changes. |
| Illustrative financing after the median grant | 2,500,000 new shares raise the denominator to 12,500,000; 175,000 options now represent 1.4% | This assumes no option-pool top-up, conversion or other issuance. Real rounds are more complex. |
The second and third rows are alternatives, not grants made together. At the median grant size, the option reserve falls by 175,000 shares. At the 75th percentile size, it falls by 426,000. A founder who ignores the reserve left for future employees can turn a generous first offer into an unexpected board and financing negotiation. An employee who hears only a percentage may not realize that a later issuance can reduce that percentage even if their option count stays the same.
The next investor is a third party in that conversation. A financing proposal can ask a company to enlarge the unallocated option reserve before new money enters. That choice determines how much ownership existing holders bear in dilution. Carta’s pool guide says pools of 10% to 15% are common, but argues for sizing against an actual 12- to 18-month hiring plan. A 4.26% first grant inside a 12% illustrative pool leaves 7.74% for everyone who follows. If a startup expects to hire a technical lead, a commercial lead and a product team, the founder needs to model those grants before promising the first one. The candidate needs to know whether a pool top-up is likely to alter the percentage used in negotiations. No public median resolves the allocation between those people.
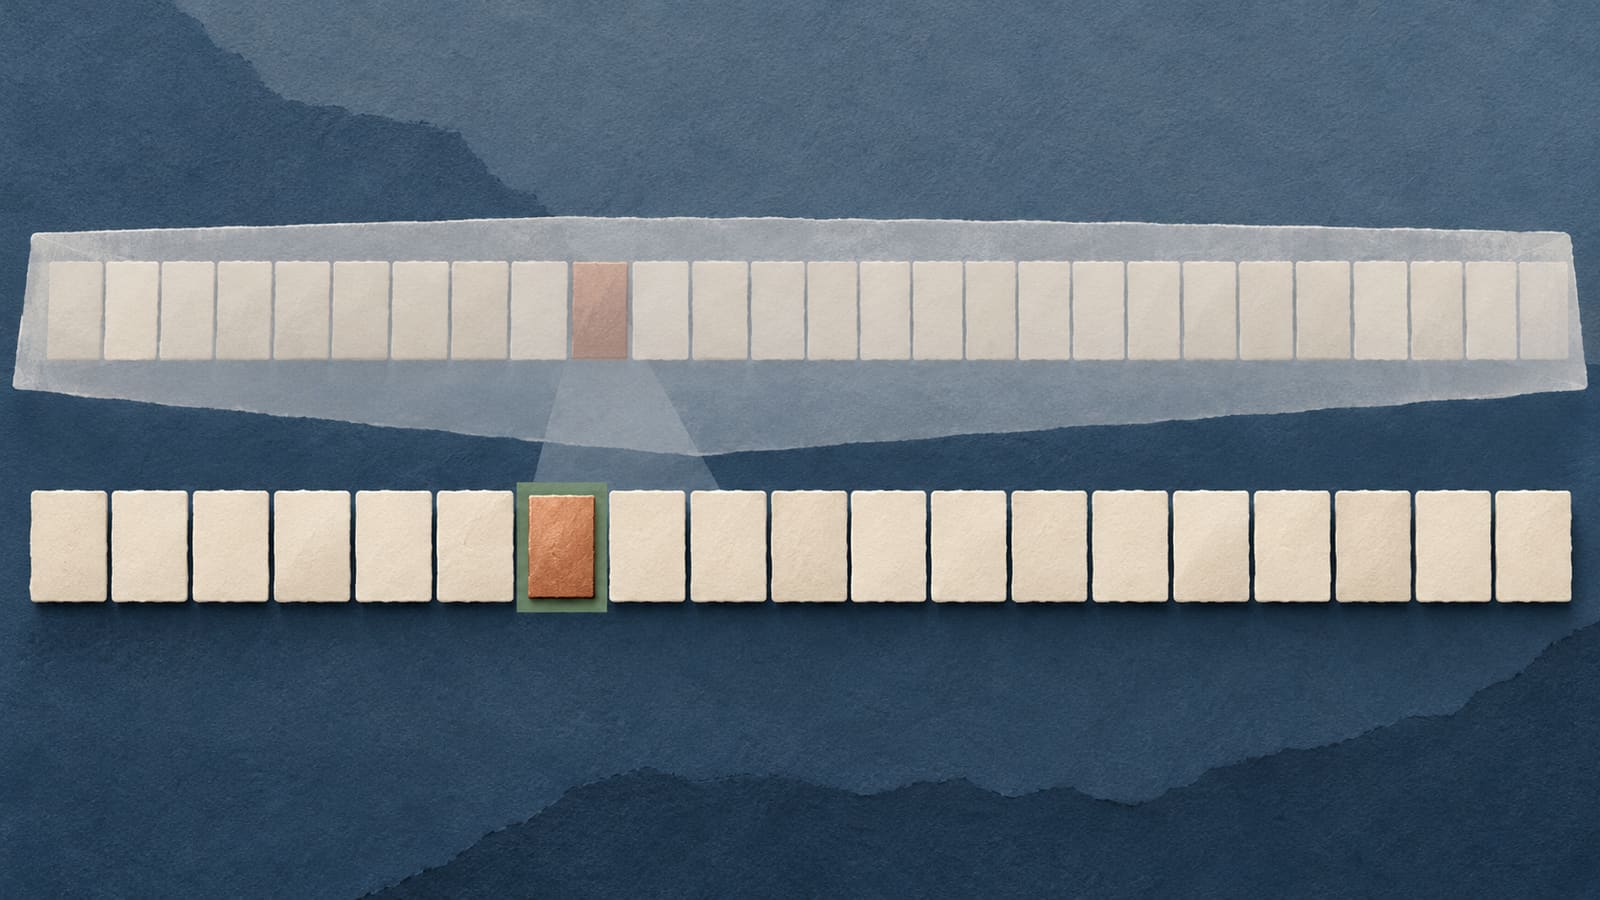
AI-generated editorial illustration. The repeated copper tile represents the same hypothetical grant before and after a larger share denominator, not two grants or an observed company cap table.
Real cap tables add complications. A real company may create new preferred shares, change the option pool before a priced round, convert SAFEs, issue refresh grants or have rights that affect proceeds. The worker’s economic outcome depends on those terms and on a sale or liquidity event, not on a tidy multiplication of headline valuation by grant percentage. Treat the table as a set of questions for the actual cap table, not a value estimate.
Salary and ownership are different kinds of pay
The cash and the options run on different clocks. Cash salary arrives through payroll. Options typically vest over time and become exercisable under the grant agreement. Carta’s stock-option explainer says a four-year vesting schedule with a one-year cliff is common among corporations on its platform. That convention is not the terms of a particular offer. A worker who leaves before the cliff may vest nothing; someone who leaves later may face a deadline and cash cost to exercise. The employee should read the actual agreement, not substitute the benchmark for it.
The U.S. Internal Revenue Service’s stock-option overview distinguishes statutory and nonstatutory options and explains that tax consequences can arise at different moments depending on the type of option and the transaction. Neither Carta’s median percentage nor a valuation headline answers the worker’s tax question. The details vary with the award and the employee’s circumstances. The practical point for the offer discussion is narrower: know what kind of right the employee is receiving, its strike price, vesting schedule and exercise window before counting it as part of pay.
The cash needed to exercise can surprise a worker who focused on the percentage. In the worksheet’s hypothetical ten-million-share company, 175,000 options at an assumed $0.50 strike price would cost $87,500 to exercise in full, before any tax or fees. That is arithmetic, not a Carta observation, a valuation or a prediction of an actual grant. Vesting and the employee’s choices could change how many options are exercisable. The figure shows why a grant can be large on paper and still require a difficult cash decision. A candidate should ask for the actual strike price and post-departure exercise terms in writing.
Liquidity may arrive much later, or never. The SEC explains that securities issued by private companies are often illiquid, with resale restrictions unlike publicly traded shares. A future acquisition, public offering or permitted secondary sale might create a path to cash; none is assured on the date of hire. An option that eventually expires out of the money has not replaced foregone salary. Even a valuable option may demand cash to exercise before the holder can sell the stock.
Founders can still make a sensible cash-equity trade. A company short on cash may need to share upside to recruit someone capable of building a durable business. Yet a low salary paired with an impressive percentage moves risk from the company to the worker. The founder should state the cash constraint plainly. The employee should be free to compare the package with a higher-cash job without being told that the valuation turns illiquid options into a bank balance.
This tension is sharper for an early worker who has no large savings cushion. A compensation plan that only works for people who can absorb a low salary and a possible exercise bill narrows the applicant pool. The cash requirement also filters who can take the job. A founder who wants applicants with different financial circumstances may need to spend more cash or examine the exercise window with counsel, rather than assume more options settle the problem. An applicant supporting a family can rationally value dependable monthly pay above a larger, illiquid stake. That preference says nothing about their ambition or belief in the product.
A smaller team does not prove an AI dividend
Carta’s report asks what AI has done to startup compensation. Its figures show a pattern among its customers, and the first-hire grant sits inside that pattern. They cannot isolate AI as the cause. LinkedIn’s smaller first-year team observation is likewise a comparison of founder cohorts, not a controlled estimate of AI’s effect on headcount. A 2021 startup launched in a different financing and hiring market from one launched in 2024. That difference can change team size without an AI tool entering the workflow.
Carta’s own May report said the median seed-stage team on its platform was four people and that average Series B headcount fell from 53 in 2023 to 45 in 2025. Series D average headcount fell 29% from its 2023 peak to 131 in 2025. A stage average does not show what one first employee produced. The October report’s 30-month run of net hiring is a reminder that small teams and continued job creation can coexist.
There is also selection in the data. Carta sees companies that use Carta, LinkedIn sees members who update profiles, and public job ads show open requisitions. None is a census of all private startup offers. The first-hire median can move because grant practices changed, because the mix of sampled companies changed, or both. Carta’s public summary says the figure continues to climb from prior analyses, but does not provide enough comparable first-hire series points in that summary to calculate a precise growth rate. It would be false precision to write one.
A reader should also resist transferring the 1.75% median across jurisdictions and stages. A pre-seed company with no revenue, a funded biotechnology venture and a profitable software business carry different cash constraints, dilution paths and sale prospects. Currency, tax treatment and employee rights differ. The current public summary does not provide a matched first-hire benchmark for each of those cases. The number starts a conversation; it cannot conclude one.
An offer meeting needs more than one number
Carta’s figures can inform the offer meeting. They cannot settle it. The founder can bring a board-approved cap table and a hiring plan. The candidate can bring the work they are expected to own and the cash alternative they would forgo. The two can then resolve a small set of concrete questions before anyone signs.
| Question | Evidence to put on the table | Decision it changes |
|---|---|---|
| Which bottleneck will this person own in the first year? | Specific product, customer, operating or hiring responsibilities; decision authority; founder handoffs | Whether the role merits a long-term ownership stake and how success will be judged. |
| What is the grant in shares and on what denominator? | Grant notice, fully diluted cap table date, option reserve, outstanding commitments | Whether the quoted percentage means the same thing to both sides. |
| Which later hires must still fit? | Twelve- to eighteen-month hiring plan and remaining reserve, with scenarios for a financing round | Whether the first grant consumes capacity needed for the next team. |
| What does the worker receive each month and each year? | Salary, benefits, vesting, cliff, strike price, option type, exercise window | Whether the person can afford the role and retain the upside if they leave. |
| What would make the grant realizable? | Company policy on liquidity and transfer, realistic financing scenarios, security class and relevant professional advice | Whether the equity is a plausible upside rather than a cash substitute today. |
The checklist is an editorial decision aid, not financial, legal or tax advice. Its purpose is to keep the exact records and assumptions in view. A founder may decide to pay more cash and issue less equity. Another may reserve a larger grant for a hire who must build a core product and accept years of illiquidity. The candidate may prefer certainty. None of those choices can be read from Carta’s median alone.
The offer letter can fit “1.75%” on one line. Before signing, the first employee needs the share count, the cap table date and the option terms on the next pages. The founder needs a pool that still covers the next hires. If either set of pages is missing, the attractive number is still an unfinished offer.